Algorithmic Futures Portfolio — 12 Strategies on One Prop Account
End-to-end systematic stack for CME futures, from 82M one-second bars to 12 intraday strategies sized to survive a $2,000 trailing-drawdown rule, executed live through NinjaTrader 8.
The problem
Prop-firm accounts are closed by drawdown, not by a weak Sharpe ratio. One profitable strategy usually can’t be sized up without breaching the trailing-drawdown limit, so the real target is the highest monthly income at the contract count the drawdown budget can fund. That means combining strategies whose losing streaks don’t overlap, and measuring drawdown the way the firm does: intraday and marked to market.
What I built
Sole engineer: research, backtesting, portfolio sizing and live execution.
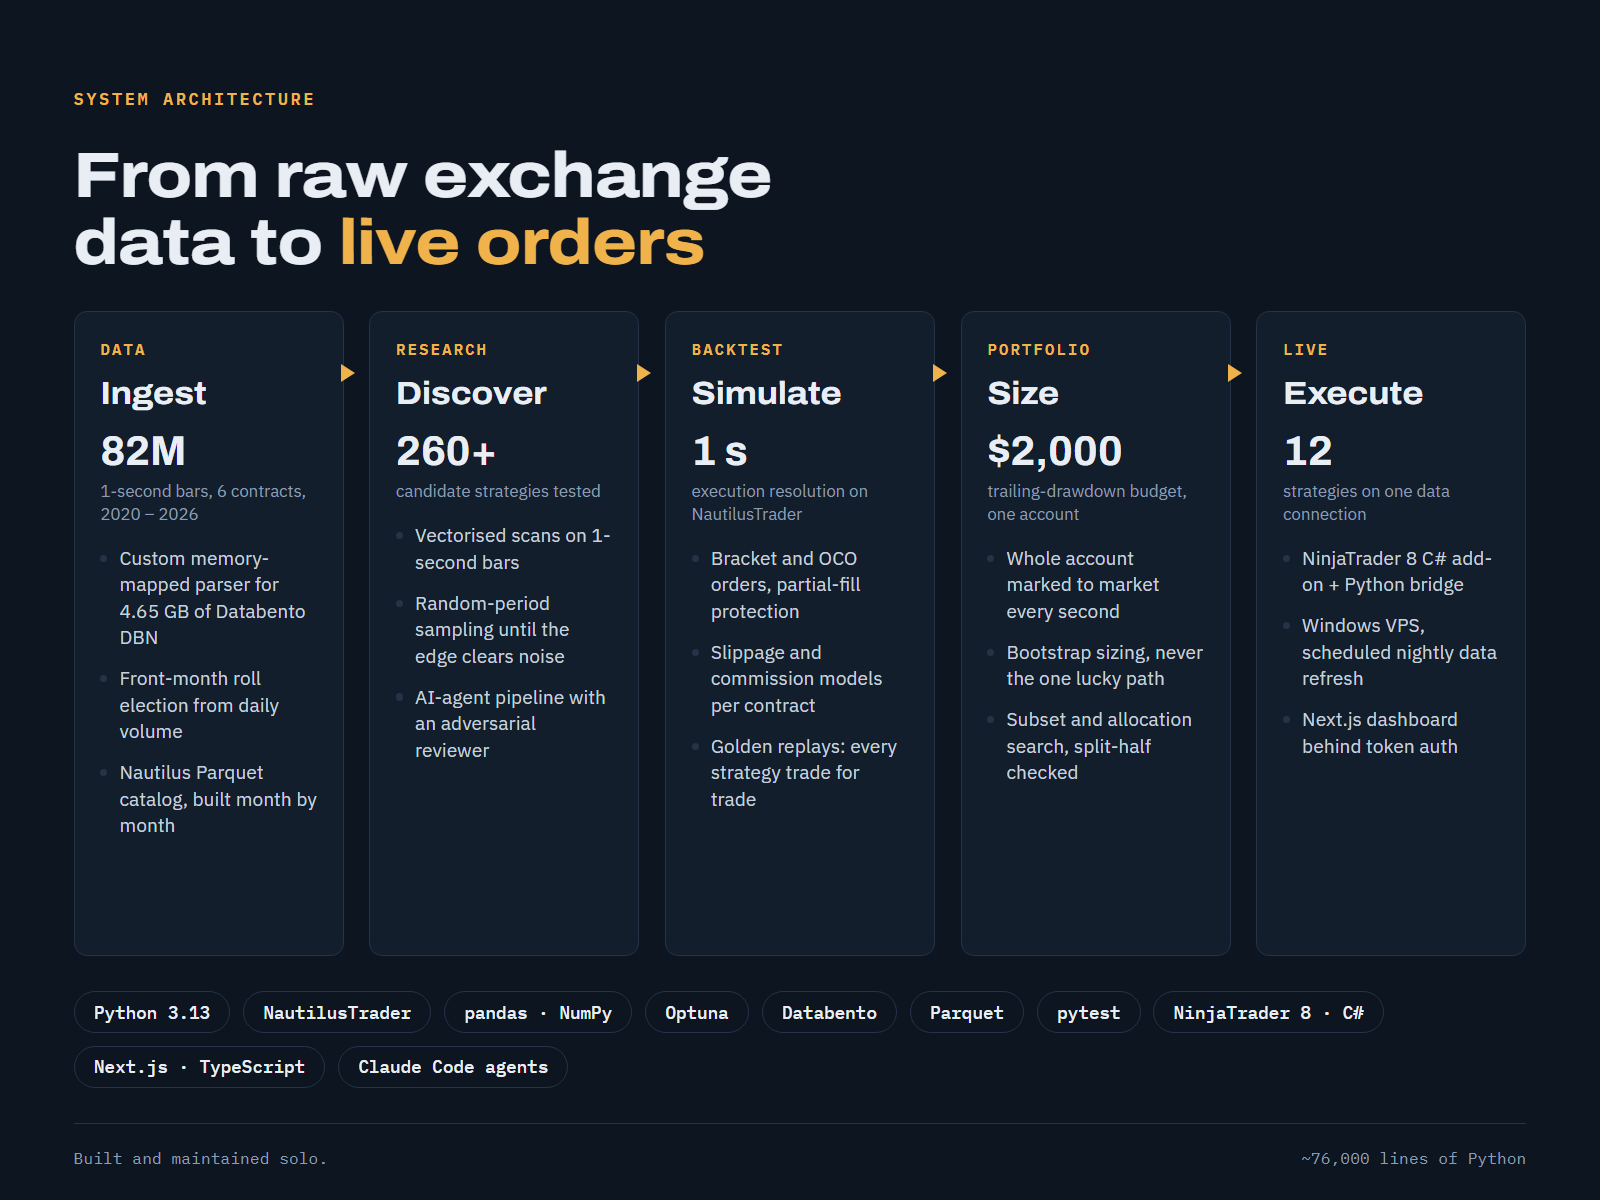
- Data pipeline: a custom parser for 4.65 GB of Databento 1-second data, front-month roll selection, and an 82M-bar Parquet catalog across 6 contracts (NQ, ES, YM, RTY, GC, CL).
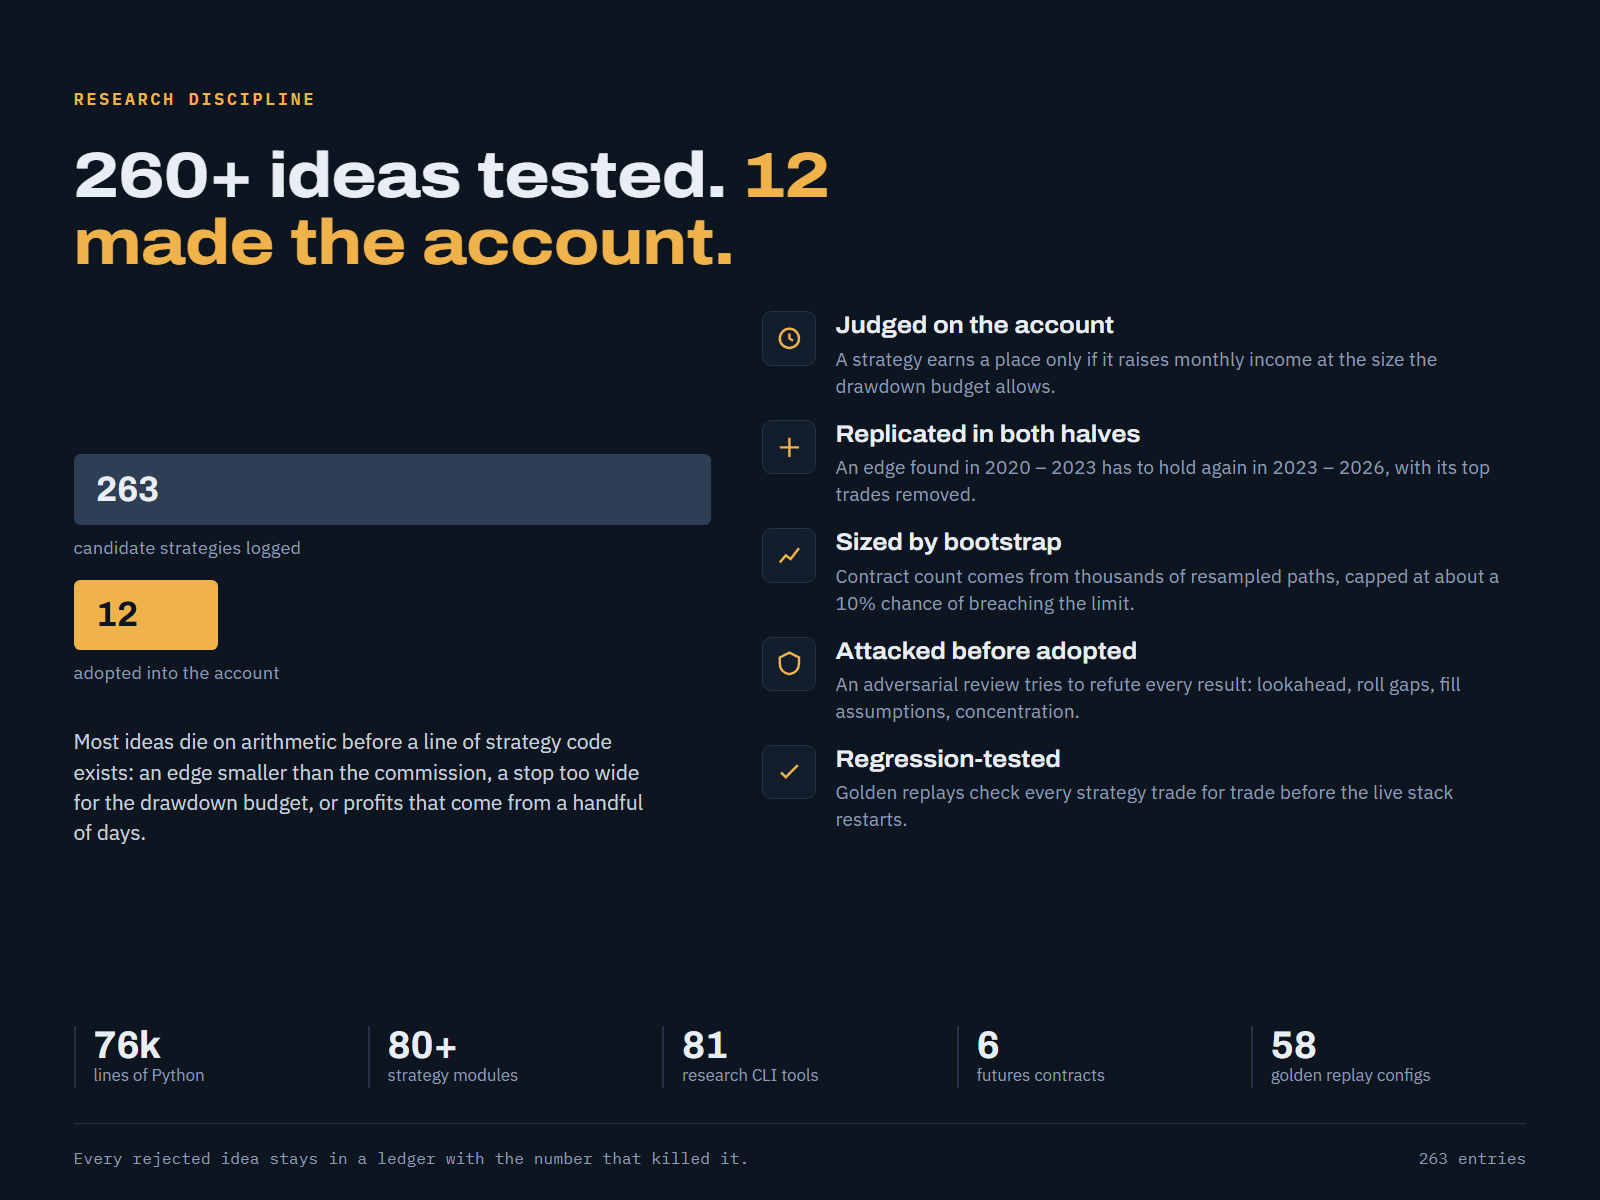
- Research: 260+ candidate strategies, each put through random-period sampling, split-half replication, concentration checks and an adversarial review that tries to refute the result.
- Backtesting: NautilusTrader at 1-second resolution with bracket/OCO orders, partial-fill protection, and slippage and commission models per contract.
- Portfolio sizing: the whole account is marked to market every second, and contract counts come from bootstrap resampling rather than the one lucky path.
- Live: a NinjaTrader 8 C# add-on with a Python bridge on a Windows VPS, plus a Next.js dashboard behind token auth.
- Safety net: a golden regression suite replays every strategy trade for trade before any live restart.
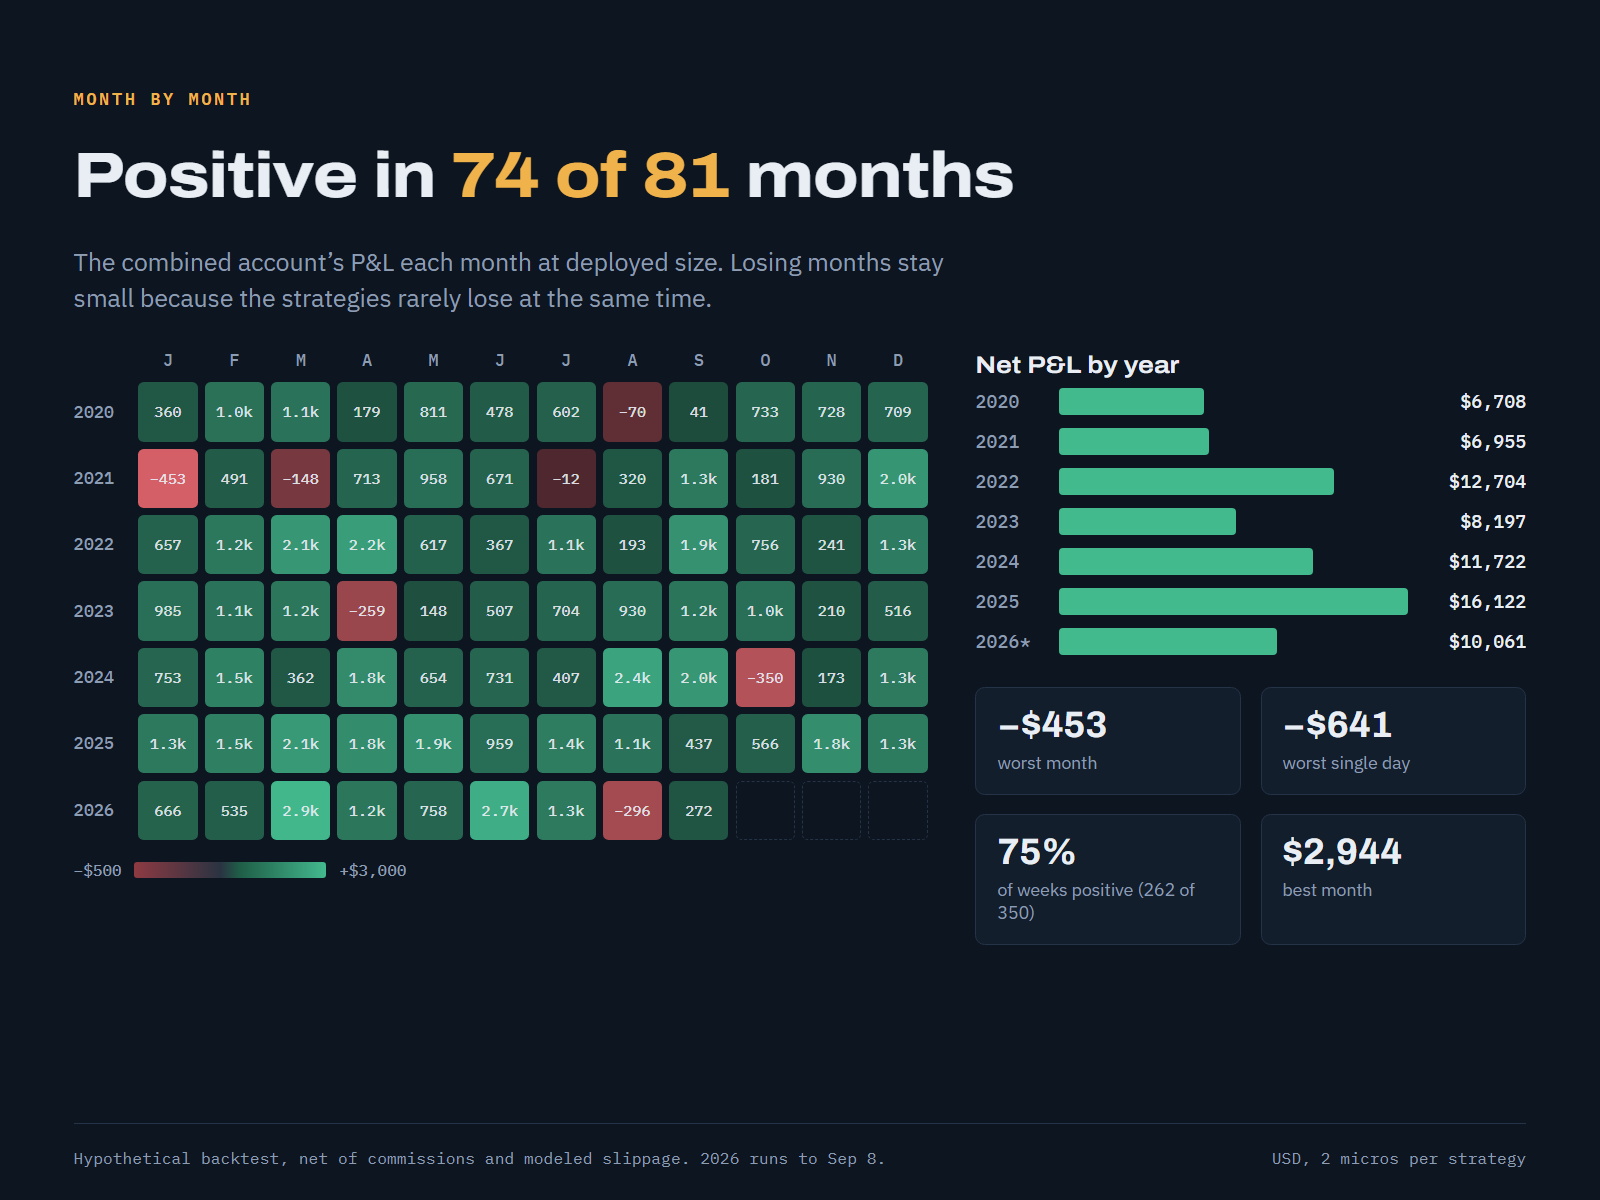
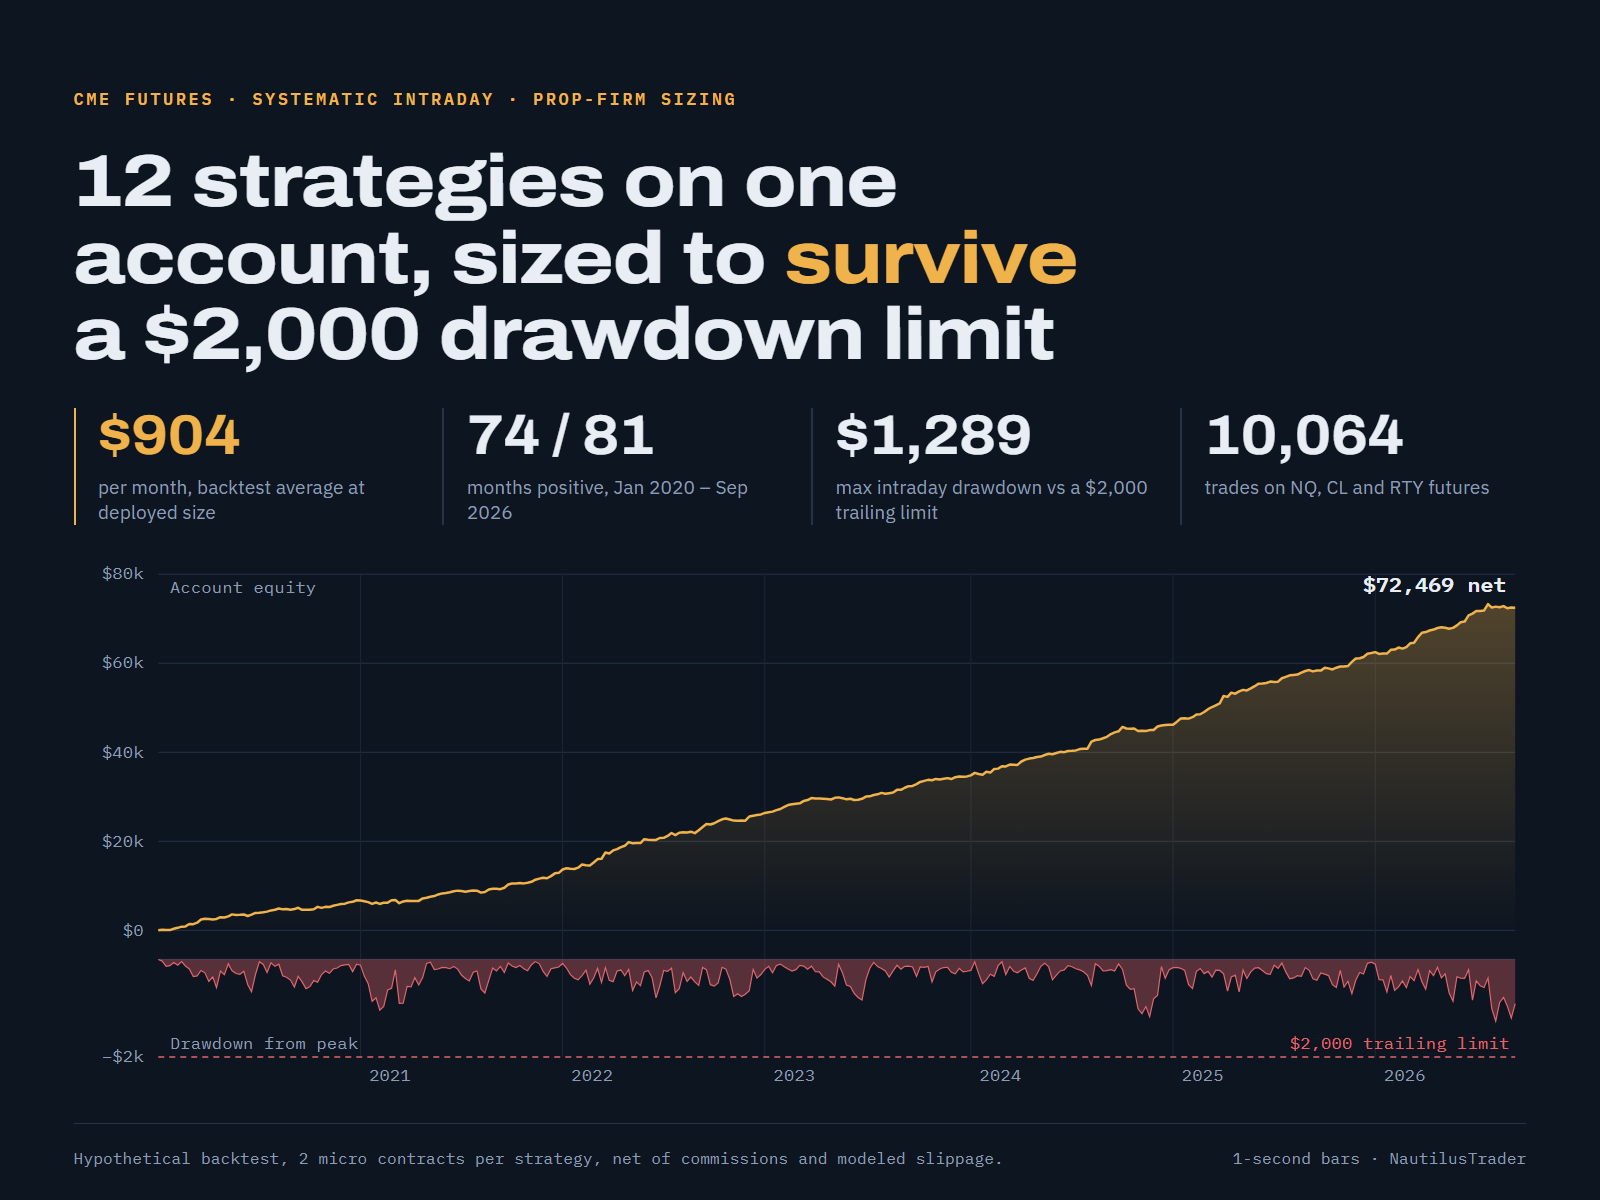
Hypothetical backtest at deployed size (2 micro contracts per strategy), Jan 2020 – Sep 2026, net of commissions and modeled slippage. Not a promise of future results.
Artifacts from this project
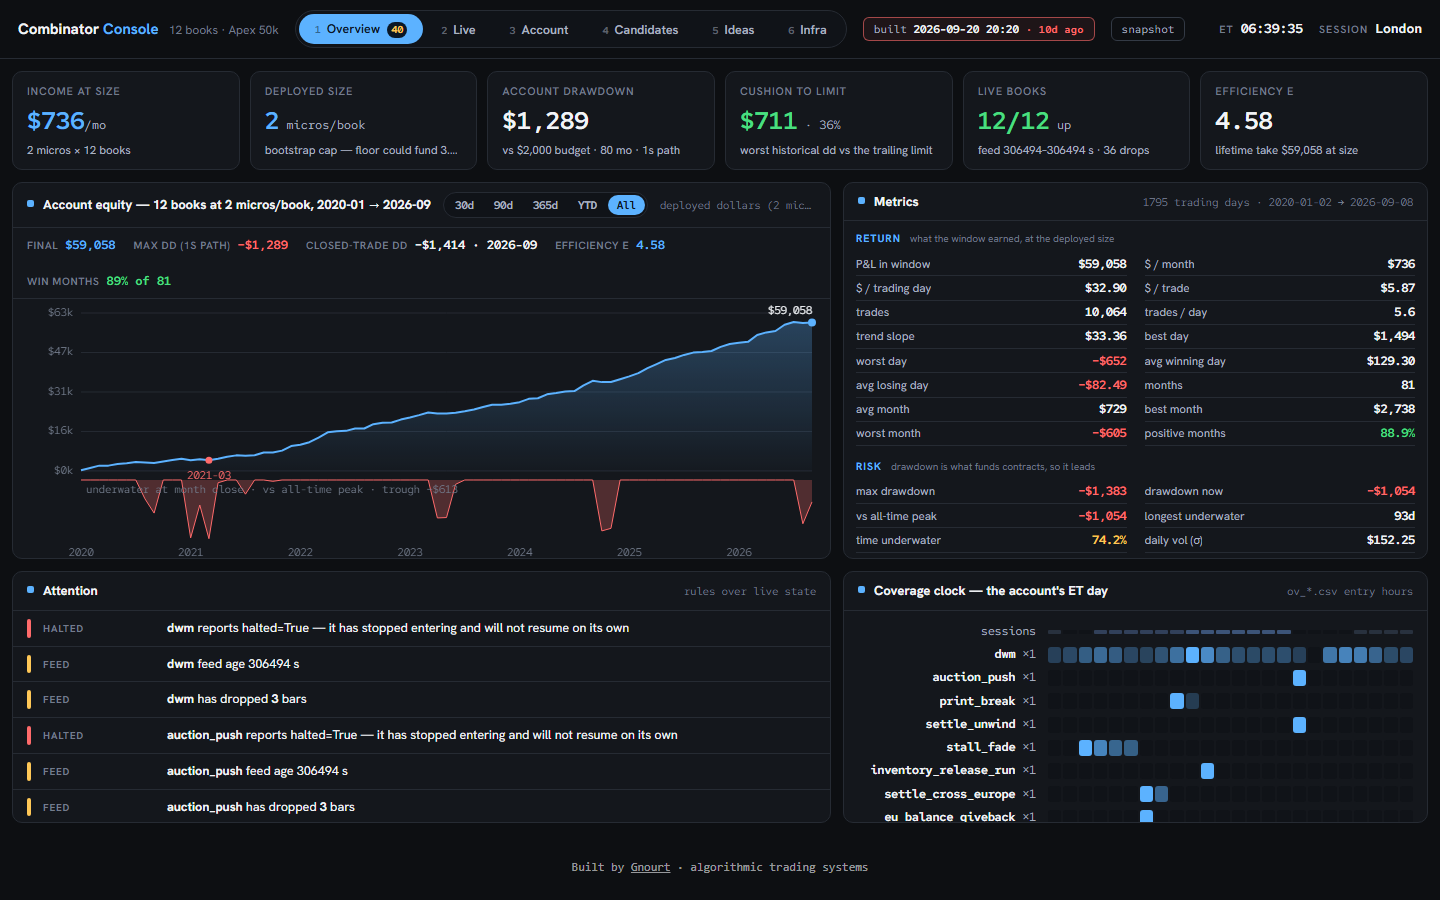
Combinator Console — futures portfolio dashboard
Snapshot of the operations console for a 12-strategy NQ futures portfolio: equity and drawdown at deployed size, risk metrics, live-feed alerts and a session coverage clock.
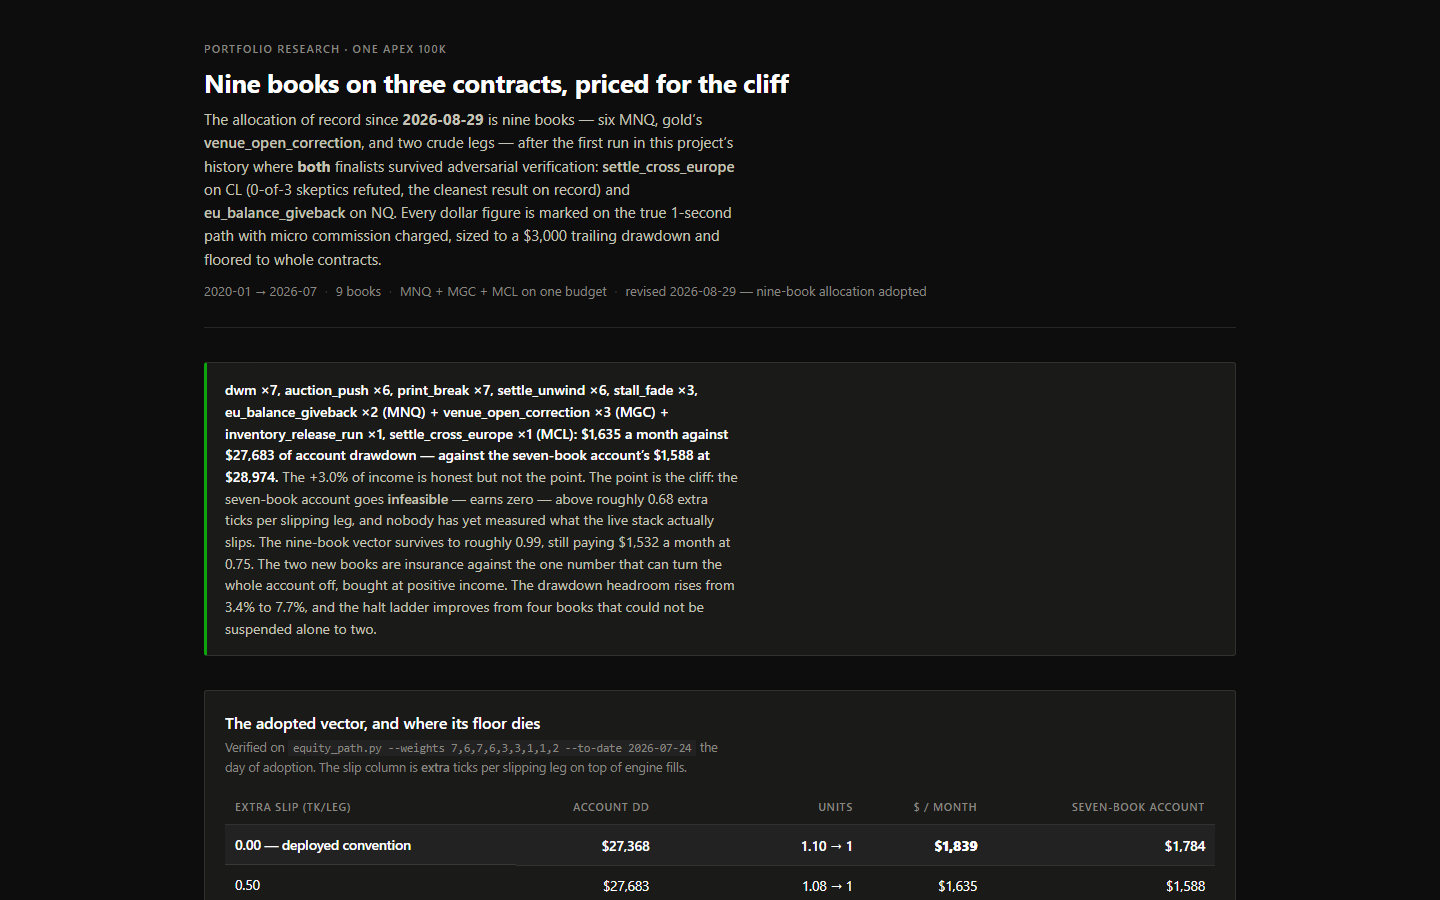
Futures Portfolio Research — nine books, one prop account
Allocation write-up for a nine-strategy MNQ/MGC/MCL portfolio sized to a prop-account trailing drawdown, including the slippage cliff past which the account stops being feasible.